Cannabis Cash Flow Management: 7 Financial Metrics to Track
Cannabis Cash Flow Management: 7 Financial Metrics to Track
Cannabis business owners can have strong sales, full shelves, and growing customer demand—and still struggle to pay vendors, make payroll, cover taxes, or fund the next stage of growth.
That is because revenue is not the same as cash.
For dispensaries, cultivators, manufacturers, distributors, and vertically integrated cannabis businesses, cash flow management is especially important. Inventory purchases, payroll, rent, licensing costs, security, compliance expenses, state taxes, and federal tax exposure can all put pressure on working capital. In addition, Section 280E may create a federal tax burden that does not align neatly with the profit shown on a standard income statement.
The businesses that make better decisions are not simply looking at their bank balance. They are tracking the financial metrics that explain what is happening now, what may happen next, and where cash could become constrained.
Here are seven financial metrics every cannabis business should monitor.
1. Cash Position
Your cash position is the amount of cash currently available to operate the business. This may include funds in operating accounts, savings accounts, and other immediately accessible business cash, depending on how your company manages its finances.
At a minimum, leadership should know:
How much cash is available today
How much cash is reserved for taxes
How much cash is committed to upcoming payroll, rent, vendors, and debt payments
Whether the business has sufficient cash to cover its next several weeks of obligations
A healthy cash balance is not just a number in a bank account. It is the foundation for stability. Without enough available cash, even a business with strong demand may need to delay orders, miss growth opportunities, rely on expensive financing, or make reactive operational decisions.
What to watch
Track cash position weekly, and review it alongside expected cash inflows and outflows. Do not treat cash that is already earmarked for tax payments, payroll, or other required obligations as freely available for spending.
2. Operating Cash Flow
Operating cash flow measures the cash generated or used by the company’s core business activities. In simple terms, it helps answer this question:
Is the business generating enough cash from operations to support itself?
Operating cash flow considers more than net income. It reflects changes in working capital items such as inventory, accounts receivable, and accounts payable.
For example, your dispensary may report a profitable month. But if you made a major inventory purchase, have not yet collected on wholesale invoices, or paid several large vendors in advance, cash may still decrease.
A positive operating cash flow trend generally means the business is producing more cash than it is consuming through normal operations. A negative trend may indicate that the business is using reserves, outside investment, or financing to keep operating.
For cannabis businesses, operating cash flow should be reviewed alongside expected federal and state tax obligations. This creates a more realistic picture of how much cash is actually available for growth, distributions, capital expenditures, or debt repayment. Cannabis operators should model cash flow with an awareness of 280E, inventory needs, receivables, payables, and tax-payment timing, not merely rely on their income statement.
What to watch
Review operating cash flow monthly, with a rolling short-term forecast. If cash from operations is consistently negative, determine whether the cause is temporary, such as a planned inventory build or a sign of a larger profitability, margin, pricing, or collections problem.
3. Gross Margin
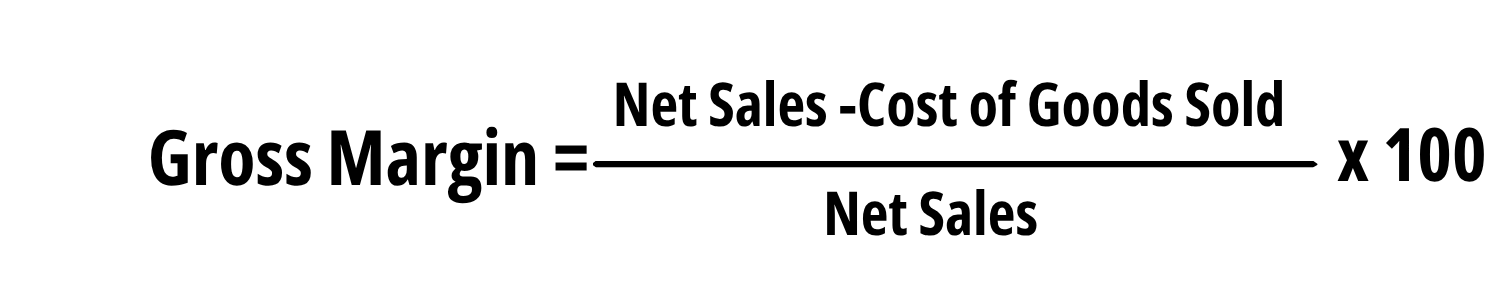
Gross margin shows how much money remains after subtracting the direct cost of goods sold from net sales.
The formula is:
Gross margin is one of the most important measures of operational performance for cannabis businesses. It can reveal whether your pricing, product mix, purchasing practices, cultivation yields, production processes, and inventory costs are supporting the business.
For a dispensary, gross margin may vary widely by product category, supplier, promotion, and location. For a cultivator, it may reflect production efficiency, yield, labor, packaging, utilities, and waste. For a manufacturer, it may help show whether materials, labor, and packaging costs are properly controlled.
Because 280E can limit deductions for many operating expenses, gross margin becomes even more important. A business may have acceptable sales but still face pressure if its gross margin is too low to support payroll, rent, compliance costs, and tax obligations.
Track gross margin at more than one level whenever possible:
Company-wide gross margin
Gross margin by location
Gross margin by product category
Gross margin by supplier or brand
Gross margin by SKU
Gross margin by cultivation batch or production line
Product-level and category-level margin reporting can help leadership identify which items contribute most to profitability and which ones may be consuming shelf space and working capital without delivering enough return.
What to watch
A falling gross margin may signal price discounting, higher wholesale costs, waste, inventory shrinkage, inaccurate costing, lower cultivation yields, or a product mix that needs attention.
4. Inventory Turnover and Days on Hand
Inventory is necessary to generate revenue. But too much inventory can trap cash that the business needs for payroll, taxes, rent, and growth.
Inventory turnover measures how often a business sells and replaces its inventory during a specific period. Days on hand estimates how long inventory remains in stock before it is sold.
The formulas are:
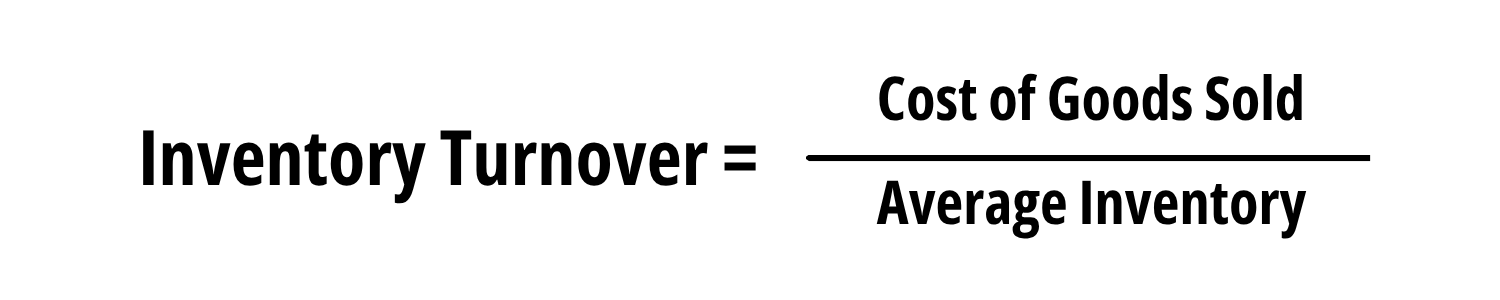
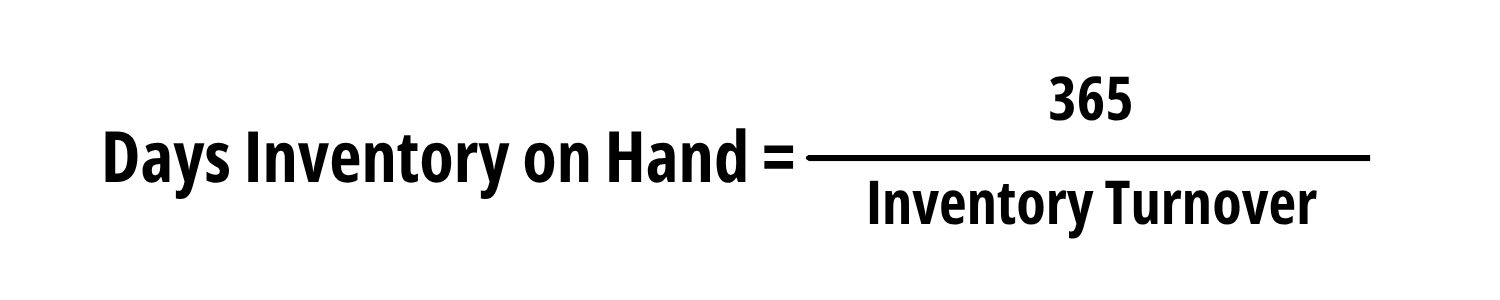
A lower turnover rate or higher number of inventory days may mean that cash is tied up in slow-moving products. This can be particularly costly in cannabis, where product freshness, packaging requirements, consumer preferences, regulatory limits, and changing product trends can all affect sell-through.
On the other hand, inventory that turns too quickly may point to understocking, stockouts, missed sales, or purchasing practices that are too reactive.
The goal is not to achieve one universal number. The right inventory level depends on your business model, product mix, lead times, supplier relationships, customer demand, and growth strategy. The key is to understand your own trends and identify where inventory is consuming too much cash.
Accurate inventory reporting matters for both financial management and tax planning. Inventory activity, product movement, and cost records should be consistently reconciled across point-of-sale systems, seed-to-sale records, physical counts, accounts payable, and the general ledger.
What to watch
Review inventory turnover and days on hand by product category and SKU, not only as a company-wide total. A strong-selling category can hide slow-moving products that are tying up a disproportionate amount of cash.
5. Accounts Receivable Aging
Accounts receivable is money owed to your business by customers. It is especially relevant for cannabis wholesalers, manufacturers, distributors, brands, and operators that offer payment terms to business customers.
An accounts receivable aging report groups outstanding invoices according to how long they have been unpaid. Common categories include:
Current
1 to 30 days past due
31 to 60 days past due
61 to 90 days past due
More than 90 days past due
A sale is not cash until payment is collected.
If your business has a growing accounts receivable balance, it may appear to be generating revenue while still lacking the cash needed to cover immediate obligations. A growing share of overdue invoices can create a significant cash-flow problem, particularly if the company must pay vendors, employees, taxes, and overhead before customers pay.
What to watch
Track total accounts receivable, overdue invoices, average collection time, and the percentage of receivables that are more than 30, 60, or 90 days past due.
Set clear customer payment terms, send invoices promptly, follow up consistently, and review credit policies before extending additional terms to customers with unresolved balances. Strong accounts receivable practices and disciplined follow-up can improve liquidity without requiring the business to increase sales.
6. Accounts Payable and Vendor Payment Timing
Accounts payable is money your business owes vendors, suppliers, landlords, service providers, and other creditors.
Managing accounts payable does not mean delaying payments irresponsibly. It means understanding payment due dates, vendor terms, recurring obligations, and the timing of cash outflows so the business can protect liquidity while maintaining strong vendor relationships.
For cannabis businesses, accounts payable may include:
Inventory suppliers
Packaging vendors
Cultivation inputs
Security providers
Software subscriptions
Rent and utilities
Payroll taxes
Professional services
Licensing and compliance expenses
Equipment vendors
Contractors
A clear accounts payable schedule helps the business forecast when cash will leave the company. It also helps management avoid paying bills too early when cash is tight or paying too late and damaging important relationships.
What to watch
Review weekly cash requirements for upcoming bills. Prioritize critical obligations, understand which vendors offer favorable payment terms, and compare planned payments to your rolling cash forecast.
An organized accounts-payable process, clear approval controls, and accurate vendor records can give the business more visibility into cash commitments and reduce last-minute payment decisions.
7. Tax Reserve and 280E Tax Coverage
For cannabis businesses, taxes should never be an afterthought.
Because Section 280E can limit deductions for ordinary business expenses, the company’s federal taxable income may be higher than its book profit. A business that appears profitable, but has not reserved adequately for tax payments can face a serious cash crunch when estimated taxes or annual tax liabilities come due.
A tax reserve is cash set aside specifically for anticipated tax obligations. This may include federal income taxes, state income taxes, sales taxes, excise taxes, payroll taxes, or other applicable obligations.
A useful management question is:
If taxes were due today, would the business have the cash set aside to pay them without disrupting payroll, inventory purchases, or operations?
Some cannabis businesses also track a tax-coverage metric to compare operating cash flow with expected tax obligations. While the exact formula should be tailored to the company and reviewed with its CPA, the purpose is simple: determine whether the business can generate enough operating cash to meet its tax burden.
Cannabis operators should maintain a tax-aware forecast that includes estimated-payment dates, tax reserves, sales or excise tax remittance dates, inventory needs, and expected changes in gross margin. A drop in margin may reduce available cash even if the business’s tax burden does not decrease at the same pace.
What to watch
Review tax projections quarterly at a minimum and more frequently during rapid growth, expansion, margin changes, entity restructuring, or significant inventory shifts. Do not use tax-reserve cash for routine operating spending without understanding the consequences.
Turn Financial Data Into Better Decisions
Tracking financial metrics is not about creating more reports for the sake of reporting. It is about using current, accurate numbers to make stronger business decisions.
When cannabis operators understand their cash position, operating cash flow, gross margin, inventory levels, receivables, payables, and tax reserve, they can make decisions with greater clarity.
For example, these metrics can help answer practical questions such as:
Can we afford to open another location?
Should we place a larger inventory order?
Which product categories are generating the strongest margins?
Is a promotion helping sales but hurting profitability?
Do we have enough cash for payroll and taxes next month?
Are overdue invoices creating a cash-flow problem?
Should we renegotiate vendor terms?
Can we responsibly take on debt or pursue outside financing?
Is our business generating enough cash to support growth?
A monthly financial dashboard, paired with a rolling 13-week cash-flow forecast, is often one of the most effective tools a cannabis operator can use. The forecast estimates weekly cash receipts, disbursements, and ending cash balances, making upcoming liquidity needs more visible before they become emergencies.
How CIACCIA Helps Cannabis Businesses Manage Cash Flow
Cash flow management requires more than checking your bank account or reviewing a year-end tax return. It requires timely bookkeeping, accurate inventory data, reliable reporting, tax-aware forecasting, and a financial partner who understands the realities of the cannabis industry.
CIACCIA CPA helps cannabis businesses build clearer financial systems and use their numbers to guide smarter decisions. Our team can help with:
Cannabis bookkeeping and monthly financial reporting
Cash-flow forecasting and 13-week cash planning
Gross-margin and profitability analysis
Inventory accounting and reconciliation
Accounts receivable and accounts payable processes
280E tax planning and estimated-tax projections
Budgeting and scenario planning
Fractional CFO and year-round advisory support
Get Clearer About Your Cash Flow
Your business should not have to guess whether it can cover taxes, payroll, inventory, rent, or the next growth opportunity. With the right financial reporting and a proactive cash-flow plan, you can move from reacting to cash shortages to planning ahead with confidence.
Ready to gain better control of your cannabis business cash flow? Contact CIACCIA CPA today to discuss cash-flow forecasting, cannabis accounting, tax planning, and year-round financial advisory support.